• Trump sizes up another strike on Iran as shipping risk in the Strait of Hormuz mounts.
• Prelim results in the NZ Election have the National led coalition government ahead holding 67 seats of 131 – enough to form a government pending around 395,000 special votes to be counted. The official result is due on 27th November.
• Analysts are suggesting the A1 boom slump of late is a re-pricing not an unwind of overall investment.
• New attacks on oil tankers in the Strait of Hormuz have raised concerns around security of energy infrastructure in the region with tensions between Iran and United States continue despite efforts to end the conflict.
• The Bank of Japan (BoJ) is set to hike interest rates to 1.50% in December, this will be its first hike in 3 years and its first ‘3 hike year’ in 37 years.
• Australian Unemployment jumps to 4.9% in October above the 4.7% forecast removing a potential hike at the December 8th RBA meeting off the table.
• The United States Dollar (USD) has been the strongest on the main board, outperforming its main rivals. The Australian Dollar (AUD) has been the worst performer for the second week straight.

The New Zealand Dollar (NZD) briefly spiked to 0.5530 in overnight trading against the US Dollar (USD) before further risk off sentiment spooked markets once again sending the kiwi down to 0.5480 reaching long term lows. President Trump is considering another strike against Iran in cooperation with Israel with potential targets being nuclear facilities. The Fed’s tone is still hawkish with inflation out of control; the central bank will almost certainly hike rates at their 8 December meeting. This should keep the kiwi on the back foot through to the end of the month.
The current interbank midrate is: NZDUSD 0.5476
The interbank range this week has been: NZDUSD 0.5471- 0.5533
The Australian Dollar (AUD) held 1.2230 (0.8910) for the first part of the week against the New Zealand Dollar (NZD) but has since lost ground into Friday posting 1.2120 (0.8250) an early September level. Australian Unemployment fell by 43,000 in October as unemployment rose to 4.9% the highest rate since 2021. This has reinforced expectations the RBA will “hold” in December. Technically the NZD may hit resistance off the 200-day moving average as it becomes overbought and could retest levels around 0.8200 (1.2200).
The current interbank midrate is: NZDAUD 0.8231 AUDNZD 1.2144
The interbank range this week has been: NZDAUD 1.2115- 1.2289 AUDNZD 0.8137- 0.8254
The New Zealand Dollar (NZD) made improvements Thursday reaching 0.4205 (2.3770) against the British Pound (GBP) the prior week high before easing back to 0.4190 (2.3880). NZ 2-year Inflation Expectations never really rocked the boat coming in at 2.36% an increase from 2.34%, however the 1 year forecast increased to 2.92% from 2.60%, the stat offering an early look at how the RBNZ may be pricing interest rates if this worsens. UK CPI y/y printed at 3.6% in October keeping rate hike possibility on Dec 18 open.
The current interbank midrate is: NZDGBP 0.4185 GBPNZD 2.3894
The interbank range this week has been: NZDGBP 0.4158- 0.4205 GBPNZD 2.3776- 2.4045
It’s a sick looking chart from an Australian Dollar (AUD) perspective with the AUD absolutely smoked over the last two weeks. The greenback has been well supported with a Fed rate hike prediction in December and heavy “risk off” market tone due to recent fallout of AI investment. The cross 21 days ago was trading around 0.7020 mark but has fallen sharply extending declines to post 0.6655 mid-morning. Australian unemployment came in worse than the 4.7% expected at 4.9% for October dropping the portability of a hike at December RBA meeting to almost nil.
The current interbank midrate is: AUDUSD 0.6650
The interbank range this week has been: AUDUSD 0.6649- 0.6780
The Australian Dollar (AUD) has underperformed over the week against the British Pound (GBP) falling to 0.5075 (1.9700) at the close of NY. The Aussie extending losses off the weekly open price of 0.5130 (1.9500) as punters buy the safe-haven Pound. Headline UK CPI y/y printed at 3.6% in October up from 3.5% in September prompting traders to trim hopes of a December Bank of England (BoE) rate hike.
The current interbank midrate is: AUDGBP 0.5079 GBPAUD 1.9688
The interbank range this week has been: AUDGBP 0.5074- 0.5134 GBPAUD 1.9476- 1.9708
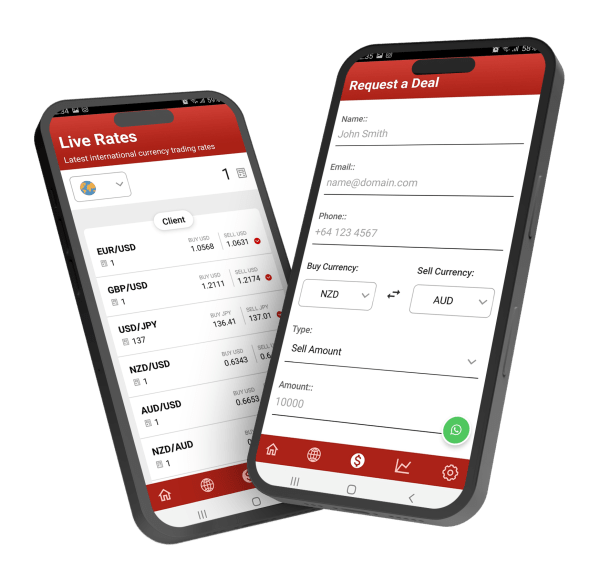
The Direct FX app has been updated to include currency charts and the highs/lows for the past 24 hours. Along with our regular market commentary, the Direct FX app also has live indicative market mid rates and a currency conversion calculator. Use the relevant link below to take you directly to the version for you, or simply search for it in the App store / Play store.