• Global markets risk improved a touch over the week but crosses against the greenback remain subdued. Not helping market sentiment was Trump’s recent comments early this morning saying he faces a “big decision” on whether to launch full-scale attacks on Iran.
• The Federal Reserve Bank raised interest rate yesterday from 3.75% to 4.0% as widely expected, the first time in 3 years. Fed chairman Kevin Warsh saying the decision comes with the economy appearing to be strengthening. “I would be hard pressed to describe the broad financial conditions as restrictive”. Warsh also went onto say he was doubling down that inflation was already falling.
• Oil prices hold just above the 100.00 mark as investors struggle to navigate heightened uncertainty over global supplies.
• The Bank of England (BoE) left interest rates unchanged last night at 3.75% in a 6-3 vote. The Central Bank floating the option of a November rate rise. If energy prices don’t retreat back to normal levels.
• The Bank of Japan (BoJ) is expected to raise rates sometime today from 1.0% to 1.25% which will be the highest level in 3 decades.
• Markets are pricing in chances of an RBA hike late September of 70.0%.
• The strongest G10 board currency this week has been the US Dollar (USD) while the worst performing currency has been the Japanese Yen (JPY). The Bank of Japan hike rates today- this could change.

The New Zealand Dolar (NZD) has had a rough week against the US Dollar (USD) extending recent declines off 0.5800 levels to clock 0.5700 late yesterday. With such geopolitical uncertainty causing volatility in the cross we think the kiwi could retest support seen at 0.5680. Earlier the Federal Reserve raised interest rates from 3.75% to 4.0% as predicted with the committee sending a strong signal, they will most likely hike further before the end of the year. NZ GDP came in at 0.2% beating forecasts of 0.1% in the quarter ending June defying contradictions of an under performing economy.
The current interbank midrate is: NZDUSD 0.5722
The interbank range this week has been: NZDUSD 0.5702- 0.5817
General central bank divergence in the New Zealand Dollar (NZD), Australian Dollar (AUD) cross widened with the RBA just that little extra bit hawkish over the week. The RBA have already delivered 3 consecutive interest rate hikes this year with markets continuing to price in more upside as inflation remains elevated. Certainly, the IMF reinforced this urging the RBA to stay hawkish on policy driven by oil and energy prices. With the RBNZ not expected to hike again this year we could see the NZD/AUD dive below the key level at 0.8000 (1.2500) over the coming days.
The current interbank midrate is: NZDAUD 0.8040 AUDNZD 1.2440
The interbank range this week has been: NZDAUD 0.8038- 0.8130 AUDNZD 1.2300- 1.2440
The New Zealand Dollar (NZD) has posted 4 consecutive weeks to the downside against the British Pound (GBP) clocking the 0.4260 (2.3480) level earlier today making a fresh early July low. The Bank of England (BoE) held interest rates steady at 3.75% in a 6-3 vote with the central bank saying further interest rate hikes were conditional upon inflationary energy rises. Certainly, the BoE face a tough decision balancing this week’s renewed energy cost rises and a cooling employment market. We think the cross could retest the massive long-term low at 0.4250 (2.3540) post Brexit in the coming days.
The current interbank midrate is: NZDGBP 0.4283 GBPNZD 2.3348
The interbank range this week has been: NZDGBP 0.4257- 0.4302 GBPNZD 2.3242- 2.3487
A “risk off” tone has sent the Australian Dollar (AUD) lower against the US Dollar (USD) to 0.7108 in morning trade, returning a touch off yesterday’s low of 0.7070. A hawkish Federal Reserve also supported buyers in USD with the Fed raising rates to 4.0% and confirming a further hike was on the cards before the end of the year. The RBA also should hike interest rates at the end of September converging central bank policy. On the docket next week is Aussie job’s data expected to print well.
The current interbank midrate is: AUDUSD 0.7116
The interbank range this week has been: AUDUSD 0.7074- 0.7165
The Bank of England (BoE) left interest rates unchanged overnight at 3.75% in a 6-3 vote. The BoE saying the interest rate outlook was conditional upon the outcomes of the war between Iran and the US suggesting further tightening may be required especially if key data like unemployment and housing remain soft. The British Pound (GBP) fell through the 100-day moving average at 0.5305 (1.8850) before posting 0.5335 (1.8750) earlier today. With the RBA pointing towards possible further hikes this year we think price could put in a move towards the June high at 0.5340 (1.8730)
The current interbank midrate is: AUDGBP 0.5325 GBPAUD 1.8779
The interbank range this week has been: AUDGBP 0.5277- 0.5298 GBPAUD 1.8875- 1.8950
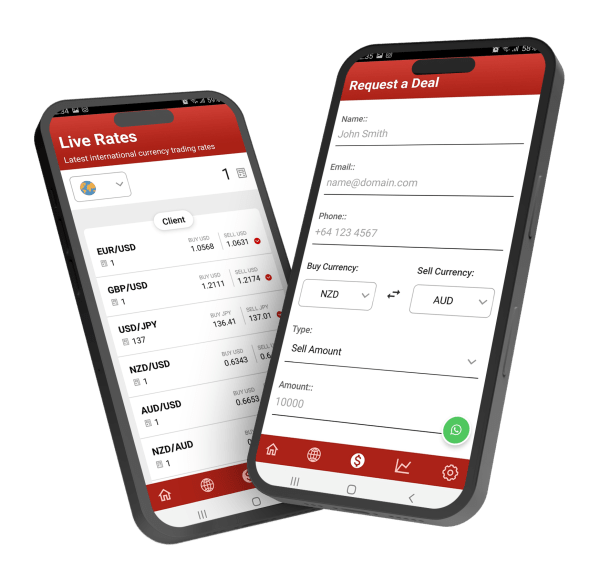
The Direct FX app has been updated to include currency charts and the highs/lows for the past 24 hours. Along with our regular market commentary, the Direct FX app also has live indicative market mid rates and a currency conversion calculator. Use the relevant link below to take you directly to the version for you, or simply search for it in the App store / Play store.